When Wall Street Broke the World: The 2008 Financial Collapse and Why It Still Matters Today

Tasfia Rahman
Research Assistant, Centre for Governance Studies (CGS)
Abstract: The 2008 financial crisis exposed the fragility of an increasingly interconnected global financial system. Risky lending, excessive leverage, the housing bubble, and institutional vulnerabilities transformed a US housing collapse into a worldwide economic crisis. Its legacy extends beyond financial markets, shaping debates over inequality, public trust, government interven-tion, debt, financial stability, and the risks underlying today’s global economy.
September 2008, A 158-year-old bank collapsed overnight. $600 billion gone, and retirement accounts vanished. Millions lost their jobs. The real cause of this lie was so simple that you could fit in a billboard: “Why rent when you can own?” In the early 2000s, 9/11 just sucker-punched the US economy and the wall street kind of Twitchy. To boost an economy grappling with poor growth, the Federal Reserve slashed the interest rate nearly to zero.1 The result was that a large number of people started borrowing and buying houses. Housing prices were rising steadily, creating widespread confidence in the property market, while banks and other financial institutions expanded access to mortgages, extending loans to an increasingly broad range of borrowers.
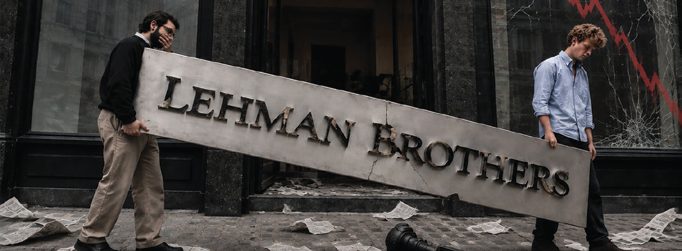
What can go wrong? House prices never fall. What the US couldn’t predict was that the very policy that they took to boost their Economy would be the very reason for the collapse of the World Financial Market. As the significant drop-in interest rates enabled banks to lend more to borrowers, these also included “Subprime mortgages,” which were loans given to borrowers with weaker credit histories. Traditionally, banks turned down Subprime borrowers as they were considered too risky. The looming recession encouraged banks to expand risky lending practices, including mortgages given to borrowers with weak financial backgrounds. Since rising housing prices created confidence that properties could always be resold, lending standards weakened dramatically, turning homeownership into a widespread financial gamble. This led to the creation of a housing bubble in the late 1990s. At first it was a whisper. A missed mortgage and an empty condo somewhere in Louisiana, and then came the wave. Home prices were falling. For years, the housing market was like a Jenga Tower built on lies, leverage, and wild optimism.2 By early 2008, the subprime mortgages and risky financial deals started to implode. Panic spread like wildfire. The financial crisis intensified dramatically in September 2008, as the collapse of major financial institutions exposed the deep vulnerabilities within the global financial system. On September 7, 2008, the U.S. government placed Fannie Mae and Freddie Mac, two government-sponsored enterprises responsible for a significant share of the American mortgage market, under federal conservatorship. The decision effectively nationalized the institutions to stabilize them and prevent further disruption in the housing finance sector. The crisis escalated further on September 15, 2008, when Lehman Brothers, one of the oldest and largest investment banks in the United States with a history spanning 158 years, filed for bankruptcy after the Federal Reserve and the U.S. government declined to provide financial assistance. The collapse of Lehman Brothers represented the largest bankruptcy in American history and triggered severe panic across global financial markets. If Lehman can die, anyone can. In the following weeks, financial instability spread rapidly across international markets. Stock exchanges around the world experienced extreme volatility as investors lost confidence in the stability of major financial institutions. Banks became increasingly unwilling to lend to one another except at extremely high interest rates because of uncertainty regarding their exposure to toxic assets. As a result, global credit markets effectively froze, limiting the flow of capital necessary for businesses and consumers.3 By late 2008, there was a full collapse, and the shockwave did not stop at Wall Street. Across Europe, governments rushed to save failing banks as fear spread that one financial collapse could bring down the entire global economy. Ultimately, the 2008 financial crisis evolved from a collapse in the U.S. housing market into a worldwide economic downturn. The failure of major financial institutions, the freezing of global credit markets, and the extensive government interventions marked the beginning of the Great Recession, the most severe global economic crisis since the Great Depression of the 1930s.In response to the escalating crisis, the Bush administration introduced the $700 billion Troubled Asset Relief Program (TARP) on October 3, 2008, to purchase distressed financial assets and provide emergency support to struggling financial institutions. Banks were too big to fail. If they collapsed, the entire global economy would collapse. However, the crisis had already expanded beyond the United States and developed into a global financial emergency.4 Although the world eventually recovered from the 2008 financial crisis, its consequences continue to shape the global economy today. The crisis revealed that modern financial markets are deeply interconnected, meaning that a problem originating in one sector of one country can quickly spread across borders. The collapse of the U.S. housing market did not remain an American problem; it disrupted banks, governments, businesses, and households worldwide. This interconnectedness remains one of the defining characteristics of today’s global economy. One of the most important lessons from 2008 is the danger of excessive debt and financial speculation. Today, governments, corporations, and households carry historically high levels of debt. While the sources of risk have changed, concerns remain about financial stability. Instead of subprime mortgages, current vulnerabilities include highly leveraged corporations, fragile banking institutions, shadow banking systems, and risks emerging from commercial real estate markets.
“In an interconnected world, the shockwavesof a crisis anywhere can become the reality ofeveryone.”
The crisis also transformed the relationship between governments and financial institutions. In 2008, governments intervened with massive bailouts because some banks were considered “too big to fail.” This created a debate that continues today: should governments rescue financial institutions to prevent economic collapse, or does doing so encourage reckless behavior by protecting institutions from the consequences of their own decisions? The legacy of 2008 can also be seen in today’s rising public distrust toward financial institutions and economic inequality. Many ordinary citizens lost homes, jobs, and savings, while large financial institutions received government support. This contributed to political dissatisfaction, increased skepticism toward globalization, and demands for stronger economic accountability. Furthermore, the crisis changed how central banks operate. The Federal Reserve and other major central banks now play a much larger role in managing economic shocks through interest-rate policies, liquidity support, and emergency interventions. However, the same low- interest-rate policies that helped economies recover after 2008 also contributed to new challenges, including asset price inflation and concerns about financial bubbles. The lessons of 2008 cannot be understood only through the collapse of banks and financial markets. They represent a larger reality of the modern world: no crisis remains isolated anymore. The COVID-19 pandemic brought the world to a standstill, disrupting human connections, global mobility, and economic activity. The Russia–Ukraine war exposed Europe’s dependence on external energy supplies and reshaped the global energy landscape. The instability surrounding the Strait of Hormuz has once again demonstrated how a single geopolitical flashpoint can send shockwaves through global oil and gas markets. Whether it emerges from a pandemic, a battlefield, an energy corridor, or a financial institution, a crisis in today’s world does not respect borders. History has repeatedly shown that periods of stability can create a dangerous sense of confidence. Beneath the surface, new vulnerabilities continue to develop through debt, geopolitical rivalry, economic dependence, and financial complexity. The next global disruption may not arrive in the form we expect, but one certainty remains: in an interconnected world, the shockwaves of a crisis anywhere can become the reality of everyone.
Endnotes
1 Elliott, L., & Seager, A. (2008, December 16). Federal Reserve slashes interest rates to nearly zero. The Guardian. https://www.theguardian.com/business/2008/dec/16/federalreserve-interest-rates-cut 2 Investopedia. Subprime meltdown: Definition, causes, and effects. Investopedia. https://www.investopedia.com/terms/s/subprime-meltdown. asp 3 Khosla, S. (2013). Understanding the 2007–08 financial crisis, the story of the housing bubble and bust: An empirical analysis. SSRN. https://papers.ssrn.com/sol3/papers.cfm?abstract_id=61065064 Hagan, M. (2019). Troubled Asset Relief Program (TARP). EBSCO Research Starters. https://www.ebsco.com/research-starters/economics/troubledasset-relief-program-tarp